What would you like a normal week in retirement to look like? More time with family, travel, a quieter routine or the freedom to pursue a personal interest? These questions are a useful starting point because your financial plan needs to support a real way of living.
Retirement planning brings together your expected expenses, existing resources and the time available to prepare. It works best when the assumptions are written down and revisited, rather than reduced to a single number that never changes.
Begin With the Lifestyle and Expenses
List the household expenses you expect to continue after retirement: groceries, utilities, transport, home maintenance and healthcare. Add occasional costs such as travel, family celebrations or replacing a vehicle.
Some expenses may reduce, while others may increase. Avoid assuming that the end of your working life will automatically make your household inexpensive to run. A realistic budget makes the planning conversation more useful.
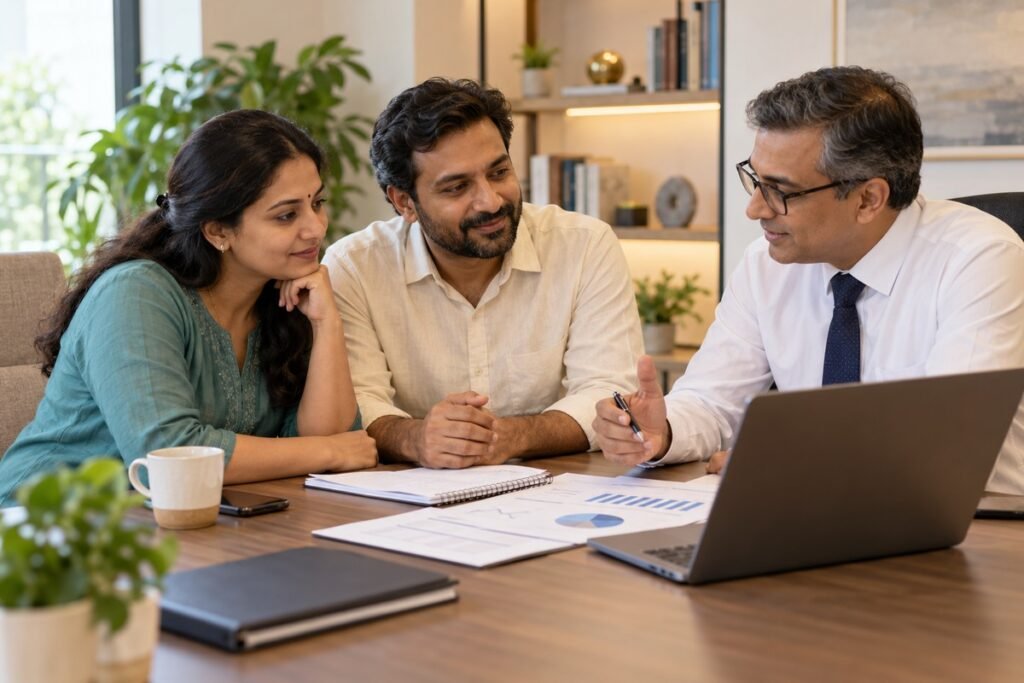
[Image: retirement-budget.jpg — Couple reviewing their retirement budget]
Caption: Start with everyday needs and the lifestyle you want your retirement plan to support.
Allow for Changes in the Cost of Living
Inflation reduces what a fixed amount of money can buy. This means today’s monthly budget should not simply be carried forward unchanged into a retirement date many years away.
For illustration, ₹40,000 of monthly expenses would become approximately ₹71,634 after ten years if prices rose by an assumed 6% every year. This is a mathematical example, not an inflation forecast. Actual costs will vary across categories, and healthcare or other priorities may need separate assumptions.
Take Stock of What You Already Have
Bring together your existing savings, investments, retirement-related accounts and any expected pension income. Also record outstanding loans and other commitments. This creates a clearer view of the resources available and the work still required.
Distinguish assets intended for retirement from those reserved for education, a home purchase or another goal. Counting the same investment toward two different needs can make both plans appear more comfortable than they really are.
Build a Contribution Plan You Can Maintain
Starting earlier gives you more time to contribute and more time for investment returns, where earned and reinvested, to compound. It also gives you a longer period in which to review assumptions and make adjustments.
Decide what you can set aside consistently, then revisit the amount as income and responsibilities evolve. Investment choices should reflect the time before you need the money and your ability to tolerate fluctuations. Higher assumed returns should not be used to hide an uncomfortable savings gap.
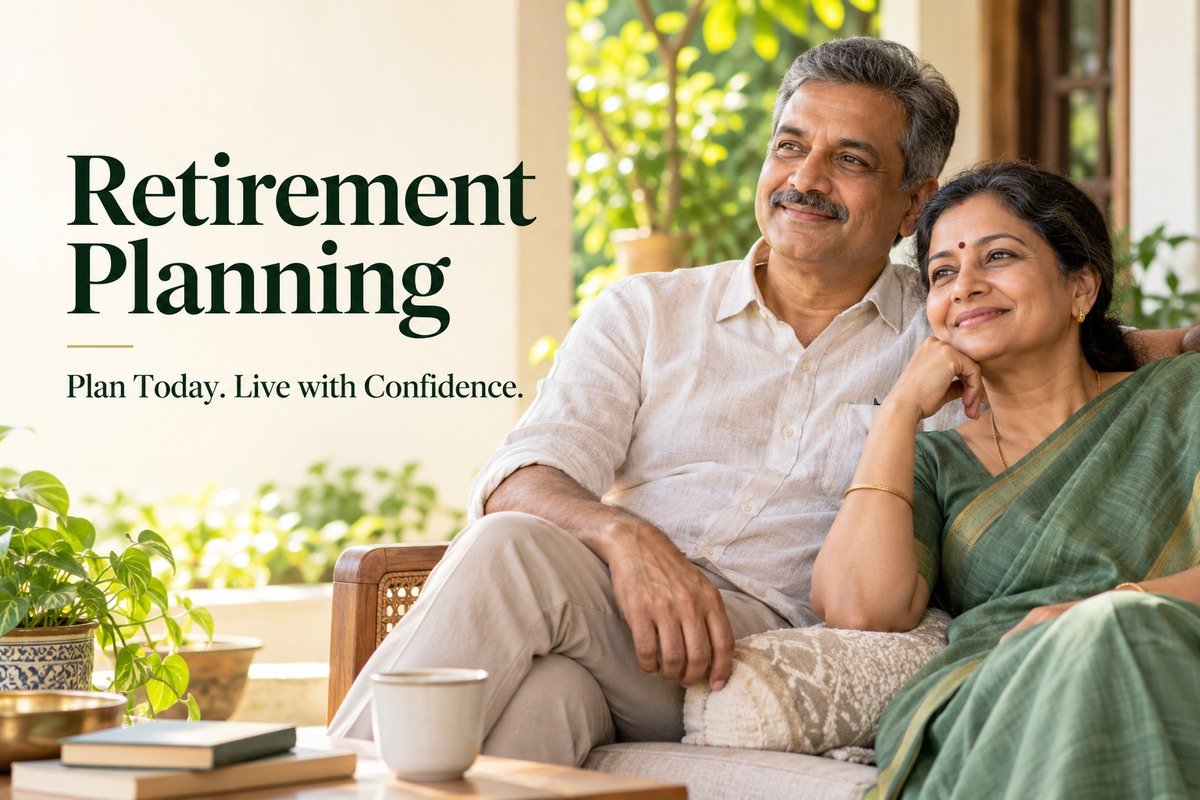
[Image: retirement-life.jpg — Retired couple walking in a garden]
Caption: Your retirement plan should reflect your own priorities and future way of life.
Plan for Healthcare and Access to Money
Unexpected expenses deserve a place in the plan. Review health insurance, likely out-of-pocket medical costs and a reserve that can be accessed when needed. Long-term investments and emergency money serve different purposes.
As retirement approaches, discuss how living expenses will be funded. A withdrawal plan needs to consider the size of the portfolio, market movements, expenses and the length of retirement. Regular withdrawals can reduce capital; they are not automatically a guaranteed income stream.
Review the Plan at Meaningful Milestones
A change in employment, a new family responsibility or an approaching retirement date can change the picture. Revisit your budget, resources and assumptions when these events occur.
It helps to document the next practical step: update an expense estimate, bring together account statements or reconsider the monthly contribution. A plan becomes easier to follow when the next action is clear.
Key Takeaway
A thoughtful retirement plan connects the life you want with realistic expenses, available resources and a contribution and withdrawal approach that can adapt over time.
Frequently Asked Questions
How much money do I need for retirement?
The amount depends on expenses, retirement age, existing resources, future income and assumptions about inflation and longevity. There is no single figure that fits everyone.
Can I start if retirement is only a few years away?
Yes. Begin by assessing the current position and the options still available. A shorter timeline makes realistic assumptions particularly important.
Give Your Retirement Priorities a Clearer Direction
Ready to put your retirement priorities into a clearer framework? Speak with Vasant Kulkarni about your current position and the lifestyle you would like to plan for.
This article is for general educational purposes and is not a personalised investment recommendation. Mutual fund investments are subject to market risks. Read all scheme-related documents carefully. Returns are not guaranteed, and past performance does not assure future results.
Financial decisions can be considered in the context of your goals, time horizon and individual circumstances rather than short-term market movements.